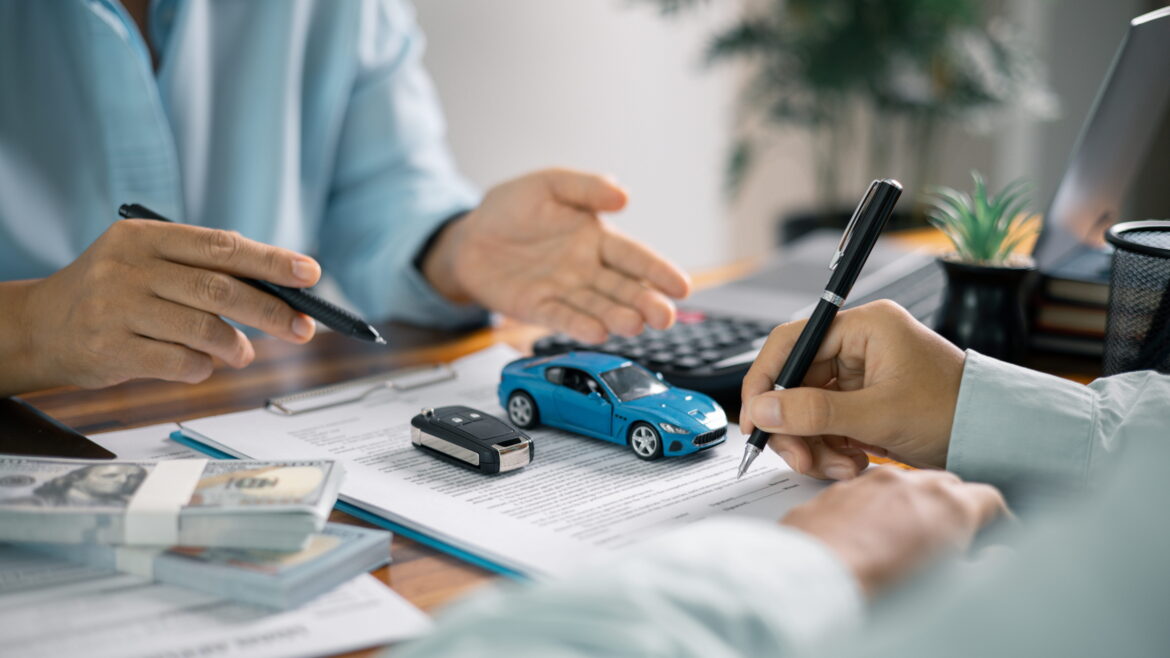
For a while now, auto leasing has been on the periphery of the credit union lending strategy, viewed as a niche product suited mainly to import brands and short-term drivers. That perception is shifting. New data shows nearly a quarter of new vehicles purchased in the first quarter of 2026 were leased rather than financed, and credit union leaders now expect that share to keep climbing as members search for payment relief in an increasingly expensive auto market.
From the systems side of auto finance, we have also seen an uptick in organizations needing to account for lease calculations within their lending and origination environments. That aligns with what the broader market data suggests: leasing is moving from a niche offering toward a more regular part of the auto finance mix.
At the same time, leasing volume moving through credit union-specific programs has surged. One national leasing platform reported booked leases climbing 68% year over year between January and April 2026. The growth signals that leasing, once treated as a side conversation, is becoming more central to how credit unions compete for auto volume.
But a larger leasing footprint brings a less visible challenge: lease transactions often involve additional variables and transaction-specific considerations that are not present in traditional auto loans. As credit unions expand into leasing, accuracy becomes more important when ancillary products, capitalized cost reductions, and varying regulatory requirements enter the transaction.
A different kind of incentive story
Historically, leasing activity tracked closely with manufacturer incentive cycles, particularly the seasonal push each fall as automakers cleared inventory ahead of new model years. That pattern looks different this year. Much of the incentive activity that once fueled leasing, especially around electric vehicles, has thinned out. The federal tax credit that helped subsidize EV leases expired at the end of September 2025, and manufacturers have already begun adjusting. Tesla, for example, raised monthly lease prices across its lineup once the credit lapsed.
That means the current rise in leasing interest cannot be explained by the usual seasonal or incentive-driven logic. Credit unions also need to consider what is required to support that demand. A growing lease portfolio introduces calculation considerations and variables that do not work the same way as a conventional installment loan.
Affordability, not incentives, is driving the shift
The more likely explanation sits closer to home. Auto loan terms have stretched well beyond what was once standard, with new loan growth increasingly concentrated at 72 months or longer. In the first quarter of 2026, the average new-vehicle loan term was 69.48 months, while more than a third of new vehicle loans were longer than 72 months.
Longer terms lower monthly payments in the short run, but they also extend the window in which borrowers owe more than their vehicle is worth. Leasing offers a structural way around that problem. A member who leases for two or three years exits before negative equity has time to build and returns to the credit union on a shorter cycle.
Industry observers have pointed to this dynamic directly, noting that leasing gives credit unions a tool to help members escape the negative equity created by today’s longer loan terms, while also bringing members back into the lending pipeline roughly twice as often as a traditional loan would.
A broader shift in who leases and why
The renewed interest in leasing is not confined to any one demographic or vehicle type. Newer research shows leasing now accounts for roughly one-in-four new vehicle transactions, driven in part by younger members who value flexibility over ownership and are more willing to trade a fixed asset for a lower, more predictable monthly payment. That preference is showing up across credit tiers.
As this audience expands, credit unions need infrastructure capable of supporting a wider range of lease transactions accurately and at scale.
The complexity behind the lease payment
The appeal of leasing may be straightforward for members, but the underlying transaction is not. Lease calculations can involve residual values, acquisition fees, taxes, capitalized costs, capitalized cost reductions, and ancillary products, each of which may need to be treated differently.
That makes sequencing critical. A capitalized cost reduction cannot simply be treated as a standalone subtraction, while ancillary products may require different treatment depending on how they are structured. As leasing volume grows, credit unions need confidence that these variables are being calculated consistently and accurately.
Regulatory ambiguity adds another layer
The calculation challenge is compounded by a regulatory environment in which requirements can vary by jurisdiction and interpretations can evolve. For lease transactions involving multiple products and adjustments, determining how each element should be treated can become particularly nuanced.
That puts greater emphasis on systems and processes that can translate changing requirements into consistent calculation and documentation logic. Accuracy is about more than producing the right payment; it is about ensuring the entire transaction is handled correctly.
What this means for credit unions going forward
None of this suggests credit unions should treat leasing as a replacement for traditional auto lending. Rather, leasing has become a necessary complement, giving members another way to manage affordability without pushing them into longer loan terms.
The credit unions best positioned to capture this shift will be the ones that treat leasing as a core part of their auto finance strategy rather than a seasonal offering. That means building the operational and technical capability to originate, price, and manage leases with the same rigor applied to traditional loans. As lease structures become more complex, credit unions need confidence that ancillary products are handled appropriately, capitalized cost reductions are applied in the correct sequence, calculations remain consistent, and regulatory changes can be incorporated without introducing new errors.
As affordability pressure continues to reshape how members think about vehicle ownership, leasing is no longer a fringe conversation for credit unions. It is quickly becoming a mainstream part of the auto lending toolkit, making the precision of the infrastructure behind those leases just as important as the demand for the product itself.